Category: Blog

  • Build Business Credit From Scratch: Step-by-Step Guide

    Quick Answer: Building business credit from scratch takes 6-12 months and involves registering your business, opening a business bank account, obtaining an EIN, establishing trade credit with vendors, and monitoring your credit reports. Most lenders require a business credit score of 50+ to qualify for financing.

    Build Business Credit From Scratch: Step-by-Step Guide

    If you’re launching a new business, one of your most critical tasks is establishing strong business credit. Unlike personal credit, business credit is separate from your personal finances and allows you to borrow money, secure better payment terms, and build credibility with suppliers and lenders. This comprehensive guide walks you through building business credit from zero, using proven strategies that align with SBA lending requirements.

    Why Business Credit Matters for Your Growth

    The Foundation for Business Financing

    Business credit is essential when you’re seeking SBA loans or other business financing. The Small Business Administration provides loans ranging from $30,000 to $5 million through approved lenders, but most require a minimum business credit score of 50-70 depending on the program. Without established business credit, you’ll struggle to qualify for favorable terms or larger loan amounts.

    Separate From Personal Credit

    Business credit is completely independent from your personal credit score. This means you can build a strong business credit profile even if you’ve had personal credit challenges. Conversely, your personal credit issues won’t automatically tank your business credit—though as a new business owner, you may still need to provide personal guarantees on loans.

    Access to Better Terms and Higher Credit Limits

    When you have established business credit, vendors and suppliers will offer you better payment terms, higher credit limits, and potentially discounted rates. This improves your cash flow and reduces the cost of doing business. For example, instead of paying upfront for inventory, you might negotiate 30-60 day payment terms once your business credit is solid.

    Step 1: Formalize Your Business Structure

    Choose and Register Your Business Entity

    The first step in building business credit is creating a legally recognized business entity. You’ll need to choose between a sole proprietorship, LLC, S-Corp, or C-Corp. Most small business owners choose an LLC or S-Corp because they provide liability protection and are recognized as separate entities from the owner.

    Register your business with your state’s Secretary of State office. This typically costs $50-$250 and takes 1-2 weeks. Once registered, you’ll receive your Certificate of Formation, which proves your business is a legal entity distinct from you personally.

    Obtain Your EIN (Employer Identification Number)

    An EIN is a nine-digit number issued by the IRS that identifies your business for tax purposes. You can apply for an EIN free at IRS.gov, and you’ll receive it immediately online or within a few weeks by mail. If you’re applying as an LLC or corporation (not a sole proprietorship operating under your own name), an EIN is essential for building business credit.

    File Business Licenses and Permits

    Depending on your industry and location, you may need local business licenses and permits. Check with your city and county to determine what’s required. These registrations prove you’re operating legitimately and help establish your business identity with credit reporting agencies.

    Step 2: Open a Business Bank Account and Build Transaction History

    Separate Business and Personal Finances

    Opening a dedicated business bank account is one of the most important steps in building business credit. When you use your personal account for business transactions, you make it impossible for credit bureaus to track your business’s financial activity separately. Most banks require your EIN, business registration documents, and a business license to open an account.

    Choose a business checking account that offers reasonable fees and doesn’t require a high minimum balance. Once opened, conduct all business transactions through this account—every invoice payment, vendor purchase, and revenue deposit.

    Build Consistent Account Activity

    Credit bureaus monitor your banking activity to assess business creditworthiness. Aim for regular deposits and payments over at least 6 months. Consistent activity demonstrates that your business is operational and stable. Even if you’re just starting, deposit regular revenue and pay your vendors and expenses through this account to create a positive transaction history.

    Maintain Adequate Account Balances

    Keep your business checking account in good standing with a healthy balance. Overdrafts and insufficient funds can damage your business credit before it’s even established. Most banks will report account problems to business credit bureaus, so avoid these issues at all costs.

    Step 3: Establish Trade Credit With Vendors and Suppliers

    Open Accounts With Business Suppliers

    Trade credit—credit extended by vendors and suppliers—is one of the fastest ways to build business credit. When you purchase supplies or inventory on credit and pay on time, vendors report this activity to business credit bureaus. Start by opening accounts with 3-5 vendors in your industry.

    Contact suppliers directly and explain that you’re a new business looking to establish trade credit. Request net-30 or net-15 payment terms. Many suppliers will approve new accounts with a small initial purchase and a credit application.

    Make Purchases and Pay on Time

    Once accounts are open, make regular purchases and pay them on time or early. Consistent on-time payments are the most important factor in building business credit. Payment history accounts for approximately 40% of your business credit score across major bureaus.

    Start small—$500-$1,000 purchases—and gradually increase amounts as your credit profile strengthens. Pay invoices within the agreed-upon terms, or better yet, pay early to demonstrate financial responsibility.

    Request Net Terms From Multiple Suppliers

    Don’t limit yourself to one vendor. Open accounts with competitors and suppliers in different categories. If you run a retail business, open accounts with 3-5 different wholesalers. If you provide services, open accounts with equipment and supply companies. Variety in your credit profile strengthens your overall business credit score.

    Step 4: Build Business Credit Through Strategic Borrowing

    Obtain a Business Credit Card

    A business credit card is an effective tool for building business credit, provided you use it responsibly. Unlike personal credit cards, business credit cards are reported to business credit bureaus, not personal credit bureaus. Apply for a card with a supplier or business lender and use it for small, regular purchases.

    Charge $500-$2,000 monthly to your business credit card, then pay the full balance on time. Never carry a balance or miss a payment. This demonstrates that your business can manage credit responsibly and creates a positive payment history with a major lender.

    Secure a Startup Business Line of Credit

    Many banks offer small business lines of credit specifically designed for new businesses. These typically range from $2,500 to $25,000 and don’t require personal guarantees if your business credit is strong enough. A line of credit that you occasionally use and pay on time significantly boosts your business credit profile.

    Consider a Secured Business Loan

    If you have personal savings, a secured business loan—where you deposit cash as collateral—can jump-start your business credit. You borrow against your deposit, pay monthly installments, and after 12-24 months, you have an established payment history. This strategy costs you a bit in interest but rapidly builds business credit.

    Loans typically range from $1,000 to $50,000, depending on your deposit amount. After completing the loan, you’ll have proven payment history with a major lender and a significantly stronger business credit profile.

    Step 5: Monitor Your Business Credit Reports

    Understand the Three Major Business Credit Bureaus

    Business credit is tracked by three major bureaus: Dun & Bradstreet, Equifax Business, and Experian Business. Each maintains separate records and may have different information about your business. You should monitor all three regularly to catch errors and track your progress.

    Pull Your Reports and Check for Accuracy

    You can request free business credit reports from each bureau. Review them for errors—incorrect company information, accounts you didn’t open, or missed payments you actually made on time. Dispute any inaccuracies immediately, as errors can significantly damage your credit score.

    Pull your reports every 3-4 months during the first year of building business credit. This helps you identify problems quickly and ensures positive activities are being reported correctly.

    Understand Your Business Credit Score

    Business credit scores range from 0 to 100 on most scales, though some bureaus use different ranges. A score of 70+ is considered excellent and qualifies you for most business loans. A score of 50-69 is fair, and below 50 is poor. Most SBA lenders require a minimum score of 50-75 depending on the loan program.

    Your score is influenced by payment history (40%), credit utilization (30%), length of credit history (20%), and other factors like public records and business stability (10%). Focus on on-time payments and keeping credit card balances below 30% of your limit.

    Step 6: Maintain Compliance and Professional Standing

    Pay Taxes on Time

    Tax compliance is crucial for business credit. The IRS reports delinquent tax accounts to credit bureaus, and a tax lien will devastate your business credit. File all required tax returns on time and pay what you owe. If you’re struggling with taxes, contact the IRS immediately to set up a payment plan.

    Keep Business Registration Current

    Renew your business license, EIN registration, and state registrations on schedule. Late or lapsed registrations signal to credit bureaus that your business may not be operational or well-managed. Set calendar reminders for renewal dates and take action well in advance.

    Avoid Public Records Issues

    Judgments, liens, and legal disputes appear on your business credit report and severely damage your score. Pay bills on time to avoid court judgments, maintain insurance to avoid liability claims, and resolve disputes amicably whenever possible.

    Timeline: How Long Does Building Business Credit Take?

    Building business credit from scratch typically takes 6-12 months. Here’s what to expect:

    Months 1-2: Register your business, get your EIN, open a business bank account, and apply for your first trade credit accounts.

    Months 2-6: Make regular purchases on trade credit and your business credit card, establishing a payment history. Monitor your credit reports for the first activity.

    Months 6-9: Your business credit score begins to reflect your payment history. By month 9, you should have a measurable score if you’ve been consistent.

    Months 9-12: Continue building trade credit and making on-time payments. By 12 months, most lenders will recognize you as an established business with solid credit.

    For SBA loans specifically, most programs (including 7(a) loans up to $5 million) require 12+ months of business history. However, some lenders may approve loans after 6 months of strong credit activity.

    How Glen Gould and Funding-Advisor.com Can Help

    Building business credit is just the first step toward securing funding. At Glen Gould through Funding-Advisor.com, we specialize in helping business owners navigate business credit requirements for SBA loans, lines of credit, and other capital solutions.

    Our advisors review your current business credit profile, identify gaps, and create a customized plan to strengthen your creditworthiness before you apply for loans. We also help you understand which loan programs align with your credit profile and financial situation, saving you time and rejection.

    Frequently Asked Questions

    Q: Can I build business credit without a separate business entity?

    A: Yes, sole proprietors can build business credit, but it’s more difficult. Business credit bureaus primarily track credit extended to legally registered business entities. If you operate as a sole proprietor, open accounts under your business name and EIN, and lenders and vendors may still report activity. However, forming an LLC or S-Corp makes building business credit significantly faster and more reliable.

    Q: How much does it cost to build business credit?

    A: The direct costs are minimal—$50-$250 for business registration, free EIN application, and low or no business bank account fees. However, if you take out a secured loan to build credit, you’ll pay interest (typically 5-15% annually). Trade credit and business credit cards cost nothing if you pay on time. The total investment is typically $200-$2,000 in the first year.

    Q: Will personal credit affect my business credit?

    A: Your personal and business credit are separate, but as a new business owner, most lenders require a personal guarantee on loans. This means they’ll review your personal credit as a secondary factor. However, even with imperfect personal credit, strong business credit can qualify you for funding. Focus on building excellent business credit, and lenders will weigh it heavily in their decision.

    Q: What’s the fastest way to build business credit?

    A: The fastest approach combines multiple strategies: open trade credit accounts with 3-5 vendors, get a business credit card, and take out a small secured loan simultaneously. Make all payments on time and monitor your reports monthly. This concentrated effort can establish a measurable business credit score within 4-6 months instead of 12.

    Q: Can I get an SBA loan with newly built business credit?

    A: Most SBA loan programs require 12+ months of business history, though some lenders may approve loans after 6 months with strong credit activity. The SBA 7(a) loan program, which offers loans up to $5 million at favorable rates (typically 2-3% above prime), usually requires a minimum business credit score of 50-70 and established payment history. Once you’ve built credit following these steps, you’ll qualify for most SBA programs.

    Frequently Asked Questions

    Get Expert Business Funding Guidance

    Book Free Strategy Call or call 850-990-0053
    Related Reading

  • Business Funding Denied: Rebuild Your Credit & Reapply Successfully

    Quick Answer: When your business funding is denied, review the lender’s reason code, spend 3-6 months strengthening your business credit and personal finances, then reapply with a revised application addressing the specific rejection factors. Most SBA loans require a minimum 680 credit score and 2+ years in business—focus on hitting these benchmarks before reapplying.

    Business Funding Denied: Rebuild Your Credit & Reapply Successfully

    Getting denied for business funding stings. Whether you applied for an SBA loan, equipment financing, or a line of credit, rejection feels like a dead end. But it’s not. Most business owners who face funding denial can rebuild and successfully secure capital—if they understand why they were rejected and take strategic action.

    As of 2026, the SBA guarantees over $36 billion in loans annually across all loan programs. That means there’s funding available. You just need to strengthen your application and reposition yourself as a lower-risk borrower. Let’s walk through exactly what to do after a funding denial.

    Why Your Business Funding Was Denied: Understanding the Real Reasons

    Before you can rebuild, you need to know exactly why you were rejected. Vague rejections like “you don’t qualify” hide the actual barriers to approval.

    Request Your Formal Denial Letter

    The lender is legally required to provide you with a written explanation of denial. If you haven’t received one, request it immediately. This letter typically includes:

    • Specific reason codes (e.g., “insufficient credit history,” “debt-to-income ratio too high”)
    • Which credit bureau data was used
    • Whether it was a credit score, cash flow, collateral, or character issue
    • Whether the SBA rejected it or the bank denied it internally

    The reason code is gold. It tells you exactly where to focus your rebuild effort. Are you weak on business credit? Personal credit? Cash flow? Collateral? Time in business? Each requires different action.

    The Five Common Denial Factors

    Most business funding denials fall into one of these five categories:

    • Low Credit Score: Personal credit below 680 or business credit score below 75 (on Paydex scale). SBA loan programs like the 7(a) loan typically require a 680+ personal credit score.
    • High Debt-to-Income Ratio: Your existing debt payments exceed 40-50% of your gross monthly income, leaving insufficient cash flow for a new loan payment.
    • Insufficient Time in Business: You haven’t operated for at least 2 years (SBA requirement for most programs). Some lenders require 3 years.
    • Weak Cash Flow: Your business revenue is declining or irregular, signaling ability-to-repay concerns.
    • Inadequate Collateral: You can’t secure the loan with personal guarantees, business assets, or residential real estate.

    Once you identify your specific denial reason, you know your rebuild roadmap.

    Business Funding Denied: Your 90-Day Rebuild Strategy

    You don’t need to wait years to reapply. Most business owners can address denial factors within 90 days to 6 months. Here’s how.

    Fix Your Personal Credit Score (30-60 Days)

    If your personal credit is below 680, this is your immediate priority. Lenders view personal credit as a character indicator—it shows whether you pay your obligations.

    Quick wins:

    • Check your credit report at AnnualCreditReport.com (free, federally mandated). Dispute any errors immediately.
    • Pay down revolving credit card balances below 30% of limits. This instantly improves your credit utilization ratio.
    • Make all payments on time for the next 30-60 days. Payment history is 35% of your score.
    • Don’t close old credit card accounts—age of accounts matters.
    • Avoid new credit inquiries. Each hard pull can drop your score 5-10 points temporarily.

    For most people, going from 620 to 680+ takes 60-90 days of disciplined credit management. This is non-negotiable for SBA loans.

    Build Business Credit Simultaneously (30-90 Days)

    While fixing personal credit, establish or strengthen your business credit profile. Business credit is tracked separately via Dun & Bradstreet, Experian Business, and Equifax Business.

    Action steps:

    • Register for a DUNS number (free at DunandBradstreet.com) if you don’t have one.
    • Open a business credit file at the three business credit bureaus.
    • Establish trade credit: open net-30 or net-60 accounts with business suppliers (office supplies, inventory vendors).
    • Make on-time payments. Paydex score improves with positive payment history.
    • Target a Paydex score of 75+ (the SBA benchmark). This typically takes 3-4 on-time vendor payments.

    Unlike personal credit, business credit builds faster because it’s based primarily on payment behavior, not historical length.

    Strengthen Your Cash Flow Documentation (60-90 Days)

    Lenders need to see that your business can handle the new loan payment. If cash flow was your denial reason, you need to prove improvement.

    What to prepare:

    • Last 2 years of personal and business tax returns (filed, not just prepared)
    • Current year profit & loss statements (monthly, not just annual)
    • Bank statements for the last 3-6 months showing deposits and account activity
    • Accounts receivable aging (if you’re a B2B business)
    • Updated balance sheet showing your net worth

    If your cash flow is genuinely weak, you may need to either:

    • Wait 3-6 months to build stronger revenue history
    • Reduce loan amount requested to a size that fits your actual cash flow
    • Add a creditworthy guarantor (spouse, business partner, investor) to strengthen the application

    The SBA’s maximum debt service coverage ratio is typically 1.25x, meaning your cash flow must be 25% higher than your monthly loan payment. If you requested $100,000 (roughly $2,100/month payment on a 7-year SBA 7(a) loan), you need monthly business cash flow of at least $2,625.

    Addressing Specific Denial Reasons: Targeted Solutions

    Different denial reasons require different responses. Here’s how to overcome each.

    If You Haven’t Been in Business 2 Years Yet

    The SBA typically requires 2 years in operation. If you’re just under this threshold, you have two options:

    • Wait: Mark your calendar and reapply the moment you hit 24 months.
    • Explore alternative programs: The SBA Microloan program has no time-in-business requirement and offers loans up to $50,000 through community development organizations.

    If you’re at 18 months, waiting 6 months is better than chasing non-SBA lenders at 15-25% interest rates.

    If You Have Insufficient Collateral

    Some loans require collateral. If you don’t have enough, consider:

    • Using residential real estate: If you own your home, it can often secure an SBA loan. A $250,000 home with $100,000 equity can back a substantial business loan.
    • Adding a guarantor with assets: A spouse, partner, or investor with collateral can strengthen your application.
    • Requesting an unsecured option: Some SBA programs require less collateral. Ask your lender about microgrants or lines of credit under $25,000.

    If Your Debt-to-Income Ratio Is Too High

    If existing personal debt is 40%+ of your income, lenders see no room for a new payment. Solutions:

    • Pay down personal debt: Even 3-4 months of aggressive paydown can drop your ratio from 48% to 35%.
    • Increase business income: If you can document higher business revenue, your debt-to-income ratio improves mathematically.
    • Request a smaller loan amount: A $50,000 loan has a smaller monthly payment ($1,050) than $150,000 ($3,150). Fit the loan to your actual cash flow.

    Preparing Your Reapplication for Success

    After 90 days of rebuild work, you’re ready to reapply. But don’t submit the same application. Treat this as a new opportunity.

    Work with a Funding Advisor

    This is where Glen Gould’s expertise becomes invaluable. Funding-Advisor.com works with business owners to structure applications specifically for approval. A funding advisor:

    • Reviews your actual denial reasons (not just what you assume)
    • Identifies which lenders are most likely to approve your profile
    • Helps you position your business financials to address denial factors
    • Ensures your application is complete, consistent, and compelling

    Many lenders have internal approval guidelines that aren’t public. A good advisor knows which banks are flexible on credit scores, which value business credit over personal credit, and which prioritize cash flow over collateral.

    Add Supplemental Documentation

    Your new application should include:

    • Explanation letter: A brief, professional letter explaining what changed since your denial (e.g., “We paid down $30,000 in personal debt, bringing our debt-to-income ratio from 48% to 35%. Our business Paydex score improved from 60 to 78 through consistent vendor payments.”).
    • Updated financials: Current P&Ls, bank statements, and tax returns (if new ones are available).
    • Updated personal credit report: Show the improvement in your personal score.
    • Business plan or use-of-funds statement: Be specific about how you’ll use the capital and what return you expect.
    • Customer testimonials or letters: If you’re in a service business, customer references add credibility.

    Apply to the Right Lender

    SBA loans are offered by banks, credit unions, and non-bank lenders. They don’t all have the same approval criteria:

    • Community banks: Often more flexible on credit scores and collateral; better for first-time applicants with moderate profiles.
    • Credit unions: May offer SBA loans to members with lower minimum credit scores (sometimes 650-670).
    • Online SBA lenders: Faster decisions but often less flexible on underlying credit quality.

    If Bank A rejected you, don’t immediately reapply to Bank A. Find a different lender that specializes in your industry or has a better fit for your profile.

    Timeline: When to Reapply After Business Funding Denied

    The SBA doesn’t prohibit multiple applications. You can reapply immediately, but it won’t help if you haven’t addressed the denial factors.

    The 90-180 Day Rebuild Window

    • Days 1-30: Dispute credit report errors, pay down revolving debt, secure business credit file.
    • Days 30-60: Make on-time payments on all obligations. Document business credit improvements.
    • Days 60-90: Compile updated financials and documentation. Approach your original lender or a new lender.
    • Days 90-180: If still improving, continue building and reapply again with stronger metrics.

    Most advisors recommend waiting 90-120 days minimum before reapplying. Reapplying in 30 days with no changes signals you don’t understand the problem.

    Frequently Asked Questions

    Q: If I was denied by one bank, will all banks deny me?

    A: No. Different lenders have different approval guidelines. Your specific credit profile might not fit Bank A’s model but could fit Bank B’s perfectly. This is why shopping around and working with an advisor helps. Some lenders are strict on credit scores; others prioritize cash flow. Some require 25% collateral; others accept 10%. A denial from one lender doesn’t mean you’re unfundable—it means you need a better fit.

    Q: How much can my credit score improve in 3 months?

    A: Typically 40-80 points, depending on your starting position and actions. Paying off a $5,000 credit card balance when your credit limit is $10,000 (moving from 50% to 25% utilization) can improve your score 20-30 points. Six months of perfect payment history can add another 20-40 points. Getting from 620 to 680 in 90 days is realistic with disciplined effort.

    Q: Should I reapply for the same loan amount or ask for less?

    A: If cash flow was your denial reason, ask for less. The math is simple: a smaller loan means a smaller monthly payment. If you can’t afford a $200,000 loan payment, you definitely can’t afford it. Reducing your request to $100,000 cuts your payment roughly in half and improves your debt-to-income ratio. Lenders prefer approving a smaller loan to the same borrower than rejecting them twice.

    Q: Can I appeal the denial decision instead of reapplying?

    A: Generally, no formal appeal process exists for SBA loan denials. However, you can request a thorough explanation and ask if the lender will reconsider with additional documentation. Most lenders won’t reverse a denial without substantial changes to your profile. Reapplying to a different lender or waiting 90 days to rebuild is the more effective path.

    Q: What if I still don’t qualify for traditional SBA loans after rebuilding?

    A: Explore alternative funding: SBA Microloans (up to $50,000, less stringent credit requirements), lines of credit (often easier than term loans), invoice factoring (uses your receivables as collateral, not credit score), or revenue-based financing (newer option, focuses on business cash flow, not credit). Some of these options have higher costs, but they can bridge you to where you’ll qualify for traditional SBA loans.

    Get Expert Business Funding Guidance

    Don’t let a funding denial be permanent. Connect with funding specialists who’ve helped hundreds of business owners rebuild and secure capital.

    Book Your Free Strategy Call or call 850-990-0053 to discuss your specific situation and rebuild roadmap.

    Related Reading

  • How Much Business Funding Can You Qualify For?

    Quick Answer: Most small businesses qualify for $350,000 to $5 million in SBA funding, depending on loan type, revenue, and creditworthiness. Your specific funding amount depends on business age, cash flow, collateral, and the SBA program you choose.

    How Much Business Funding Can You Qualify For?

    Determining how much business funding you can qualify for is one of the most critical questions when seeking capital for your small business. Whether you’re launching a startup, expanding operations, or managing cash flow challenges, understanding your potential funding range helps you plan strategically and approach lenders with realistic expectations.

    The amount you can borrow depends on multiple factors: your business structure, revenue history, credit profile, collateral, and the specific SBA loan program you pursue. SBA-backed loans currently represent the most accessible path for small business owners, with approval rates significantly higher than traditional bank loans.

    Understanding SBA Loan Limits and Maximums

    The Small Business Administration sets specific lending limits that vary by program type. These limits determine the ceiling for how much business funding you can potentially receive. As of 2026, the SBA has adjusted its loan maximums to reflect current economic conditions and inflation.

    SBA 7(a) Loan Program Limits

    The SBA 7(a) loan program is the most popular small business lending option available. This program currently offers maximum loan amounts up to $5 million, though the average loan size hovers around $360,000. Most small business owners use these funds for working capital, equipment purchases, inventory, and real estate acquisition.

    Within the 7(a) program, the SBA offers Express loans with maximum amounts of $350,000. If you need faster approval timelines (typically 36 hours), the Express option provides expedited processing. The traditional 7(a) loan takes approximately 10-20 business days for approval but allows larger amounts.

    SBA Microloan Program Limits

    If your business is just starting or you need a smaller amount, SBA microloans max out at $50,000. These loans are ideal for startups, minority-owned businesses, and women entrepreneurs. The average microloan size is approximately $13,000, making this program perfect for initial inventory purchases, equipment, or working capital needs under $50,000.

    SBA 504 Loan Program Limits

    For real estate and equipment financing, the SBA 504 program allows loan amounts up to $5.75 million (with special-use property exceptions reaching $7 million). These loans require a 10% down payment from you and typically finance up to 90% of project costs. The 504 program is specifically designed for long-term asset financing with fixed rates.

    Key Factors Determining Your Specific Funding Amount

    While SBA programs set maximum limits, lenders evaluate multiple criteria to determine your actual funding eligibility. Your specific funding amount will be lower than program maximums based on your individual business profile.

    Business Revenue and Cash Flow

    Lenders scrutinize your business revenue and cash flow projections to ensure you can service debt. Most lenders require that your business demonstrates sufficient cash flow to cover loan payments plus operating expenses. If your annual revenue is $500,000, you’ll typically qualify for smaller loans than a business generating $2 million annually.

    The debt service coverage ratio (DSCR) is crucial—lenders generally require a DSCR of at least 1.25x, meaning your monthly cash flow must be 25% higher than your monthly loan payment obligations. This directly impacts how much business funding you can actually receive.

    Time in Business

    Business age significantly influences funding amounts. Established businesses operating 2+ years typically qualify for larger loans than startups. If your business has been operating less than one year, expect lower approval amounts—often between $25,000-$150,000 depending on the program. Businesses with 5+ years of operating history with consistent profitability qualify for the maximum program amounts.

    Personal and Business Credit

    Your credit profile determines both approval likelihood and the amount you qualify for. The SBA requires a minimum personal credit score of 640-660 for most programs. With scores above 700, you qualify for larger amounts and better rates. Business credit history, if established, also influences funding decisions.

    If your personal credit score is below 650, you may still qualify for SBA microloans or community-based lending through organizations that specialize in underserved borrowers. These programs typically offer $15,000-$50,000 rather than the larger 7(a) amounts.

    Collateral and Personal Guarantees

    The collateral you can pledge directly impacts funding amounts. If you own real estate, equipment, inventory, or investment accounts, you can use these as loan security. Lenders typically lend up to 80% of real estate value and 50-75% of equipment value.

    For SBA loans exceeding $25,000, you’ll provide a personal guarantee backing the loan with your personal assets. This guarantee allows lenders to offer larger amounts because their risk is mitigated by your personal responsibility.

    Business Purpose and Industry

    Your intended use of funds affects approval amounts. Working capital and equipment financing typically see higher approval amounts than startup loans. Certain industries—agriculture, hospitality, and entertainment—face tighter restrictions, which may reduce your funding qualification compared to a tech or professional services business in the same revenue category.

    Typical Business Funding Ranges by Stage

    Understanding typical funding amounts for your business stage helps set realistic expectations.

    Startup Businesses

    New businesses without revenue history typically qualify for $10,000-$150,000. If you’re using personal funds or investor capital as a down payment on an SBA loan, you may reach $250,000 through the 7(a) Express program. Most startup funding comes through SBA microloans, friends-and-family investments, or personal credit facilities combined with small SBA loans.

    Growth-Stage Businesses

    Businesses with 2-5 years of operating history and $300,000-$1 million in annual revenue typically qualify for $200,000-$750,000. This stage represents the “sweet spot” for SBA lending, where lenders view the business as established but still growth-oriented. Your cash flow and collateral significantly influence amounts within this range.

    Established Businesses

    Mature businesses operating 5+ years with $1-5 million in annual revenue can access $500,000-$2 million or more. These businesses often qualify for maximum program amounts if they maintain healthy cash flow and credit profiles. Many established businesses use larger loans for real estate acquisition (504 program) or significant expansion (7(a) traditional loans).

    Acquisition and Expansion

    If you’re acquiring another business or significant assets, funding needs typically range from $250,000-$5 million depending on the acquisition size. The 504 program works well for equipment-heavy acquisitions, while 7(a) loans suit diversified acquisition financing.

    Working with Funding Advisors to Maximize Your Amount

    Many business owners underestimate how much business funding they can qualify for because they don’t understand the full evaluation process. Working with experienced funding advisors like those at Funding-Advisor.com helps you present your business in the strongest possible light.

    Professional funding advisors review your financial statements, tax returns, business plans, and credit profiles to identify the right program match and realistic funding target. They often help you structure your application to qualify for larger amounts by addressing lender concerns proactively.

    Glen Gould emphasizes that many small business owners qualify for 30-50% more funding than they initially request, simply because they don’t understand what lenders can approve. Getting a professional assessment before applying prevents leaving money on the table.

    Approval Timelines and Funding Speed

    The time to receive your funding varies by program and directly impacts your planning:

    SBA Express Loans (7(a))

    Approval within 36 hours for amounts up to $350,000. You could access funds within 5-7 business days from approval. These loans are ideal when you need quick capital but don’t need the maximum SBA amounts.

    Traditional SBA 7(a) Loans

    Typical approval timeline of 10-20 business days, with funding 1-2 weeks after approval. Total timeline from application to capital in hand: 4-6 weeks. This option supports larger amounts (up to $5 million) and works best when you can plan ahead.

    SBA 504 Loans

    Longest timeline, typically 8-12 weeks from application to funding. These are specialized programs with additional requirements but offer fixed long-term rates ideal for real estate and equipment financing.

    Frequently Asked Questions

    Q: How much business funding can I qualify for with bad credit?

    A: With credit scores below 650, your options are more limited. SBA microloans (up to $50,000) through community lenders are your best option. You may also qualify for smaller amounts ($15,000-$100,000) through alternative lenders, though rates will be higher. Rebuilding your credit score to 650+ significantly expands your funding options and increases approval amounts.

    Q: Does my business need to be profitable to qualify for funding?

    A: Not necessarily. Startups with no revenue can qualify for SBA microloans and 7(a) Express loans if you have personal guarantees and collateral. However, profitability or strong revenue projections increase your qualification amount. Lenders want to see either historical profitability or realistic projections showing your business can service the debt.

    Q: What’s the minimum amount I can borrow through SBA loans?

    A: SBA 7(a) loans have no official minimum, though most lenders require at least $25,000 minimum. SBA microloans have minimums around $500 and max out at $50,000. Some alternative lenders offer smaller amounts, but SBA programs are most cost-effective for amounts above $25,000.

    Q: Can I qualify for business funding without collateral?

    A: SBA microloans and some community development financial institution (CDFI) loans require minimal collateral. For larger SBA 7(a) and 504 loans, collateral significantly improves your approval chances and increases available amounts. You may qualify without collateral if you have excellent credit and strong cash flow, but amounts will be limited to $50,000-$150,000.

    Q: How does my business type affect funding qualification amounts?

    A: Some industries face stricter lending requirements. Professional services, technology, and manufacturing typically see higher approval amounts. Hospitality, entertainment, and restaurant businesses face tighter restrictions, potentially reducing your qualification by 20-30%. Agriculture has specialized SBA programs with different limits. Your industry significantly impacts available amounts, making industry-specific funding strategies important.

    Get Expert Business Funding Guidance

    Book Free Strategy Call or call 850-990-0053

    Related Reading

  • SBA Loans & Grants for Veterans: Complete Funding Guide

    Quick Answer: Veterans can access SBA loans up to $5 million through specialized programs like the Veterans Advantage Loan, plus grants and contracting opportunities reserved exclusively for veteran-owned businesses. The SBA offers lower interest rates, reduced fees, and dedicated support to help you transition from military service to business ownership.

    SBA Loans & Grants for Veterans: Complete Funding Guide

    Transitioning from military service to entrepreneurship is a significant step, and the Small Business Administration (SBA) recognizes your unique value. The federal government has created comprehensive funding pathways specifically designed for veterans like you, offering preferential loan terms, grants, and contracting advantages that can accelerate your business growth.

    Whether you’re launching a startup or scaling an existing operation, understanding your veteran-specific funding options can mean the difference between a well-capitalized venture and one struggling for capital. This guide walks you through every SBA program available to you, the exact amounts you can borrow, and how Glen Gould and resources like Funding-Advisor.com can help you navigate the process.

    SBA Loans for Veterans: Your Primary Funding Options

    The SBA offers several loan programs tailored to veteran entrepreneurs. Unlike traditional bank loans, these options feature government backing that reduces lender risk—which means you get better terms.

    Veterans Advantage Loan Program

    The Veterans Advantage Loan is the SBA’s flagship program for veteran business owners. This 7(a) loan guarantees up to 90% of the loan amount, protecting your lender and unlocking capital that might otherwise be unavailable.

    • Maximum loan amount: $5 million
    • SBA guarantee: Up to 90% of the loan
    • Interest rates: Prime rate + 2.25% to 2.75% (significantly below conventional business loans)
    • Repayment terms: Up to 10 years for working capital, 25 years for real estate
    • Fees: 2% SBA guarantee fee (often waived or reduced for veterans)

    The Veterans Advantage Loan covers essentially any business use: equipment purchases, inventory, payroll, debt refinancing, or real estate acquisition. Unlike some SBA programs, there’s no specific industry restriction—you can start any business type.

    CDC/504 Loans for Real Estate & Equipment

    If your business requires significant real estate or equipment investment, the SBA’s 504 program (administered through Certified Development Companies) is powerful for veterans.

    • Loan structure: 50% SBA guarantee, 40% conventional financing, 10% equity required from you
    • Maximum SBA portion: $5 million for standard businesses
    • Uses: Real estate, machinery, equipment, building construction
    • Interest rates: Below-market fixed rates (typically 1-2% below prime)
    • Terms: 10 years for equipment, 20 years for real estate

    The 504 program’s major advantage is its fixed-rate structure, protecting you from interest rate fluctuations over decades. For veterans purchasing land or constructing facilities, this stability is invaluable.

    Microloan Program for Startup Veterans

    Starting small? The SBA Microloan program bridges the gap between personal savings and larger financing.

    • Maximum loan: $50,000 (average around $14,000)
    • Purpose: Working capital, equipment, inventory—no real estate
    • Eligibility: Lower credit requirements than 7(a) loans
    • Interest rates: 8% to 13% (depends on intermediary lender)
    • Repayment: 6 years average

    Microloans also include free business training and counseling through SBA-approved intermediaries, giving you operational guidance alongside capital.

    SBA Grants for Veteran-Owned Businesses

    Unlike loans requiring repayment, grants are free money—but competition is substantial. The SBA offers several grant opportunities for veterans, though availability fluctuates with federal budget cycles.

    Patriot Express Loan (No Longer Available—Updated Options)

    While the Patriot Express program was discontinued in 2019, the SBA replaced its functionality within the Veterans Advantage Loan program. However, several grant alternatives exist for veterans.

    Federal Small Business Grants for Veterans

    The SBA awards grants through multiple channels:

    • Small Business Development Centers (SBDCs): Free consulting and training for veteran entrepreneurs
    • SCORE Mentoring: Free business mentorship from retired executives
    • Boots to Business: Specialized entrepreneurship training through the Department of Defense, available to service members and veterans
    • State and Federal Grants: Many states offer grant programs specifically for veteran-owned businesses (amounts vary $5,000 to $50,000+)

    While these aren’t direct cash grants to individual businesses, the combined value of free training, mentorship, and reduced-cost resources can equal thousands in equivalent services.

    Venture Capital & Angel Investor Networks for Veterans

    Several organizations prioritize funding veteran-owned businesses:

    • Bunker Labs: Veteran startup accelerator connecting you to investors
    • Veteran-Focused Angel Networks: Wealthy veterans investing in military-connected entrepreneurs
    • Corporate Veteran Programs: Companies like Google, Amazon, and Microsoft offer grants and resources for veteran entrepreneurs

    Specialized Veterans Funding Programs & Certifications

    Beyond standard loans, being a certified veteran-owned business unlocks exclusive contracting opportunities and funding pathways.

    Service-Disabled Veteran-Owned Small Business (SDVOSB) Certification

    If you have a service-connected disability rating from the VA, you qualify for SDVOSB status:

    • Exclusive government contracts: 3% of federal contracting is set-aside for SDVOSBs
    • Enhanced lending terms: Many lenders offer better rates to certified SDVOSBs
    • Veteran Advantage surety bonds: Lower-cost bonding for government contract bids
    • Registration: VA Vendor Information Pages (VOSB registry)

    Federal contracting can generate substantial, stable revenue—and the SBA and government agencies actively support veteran contractor success.

    Veteran-Owned Small Business (VOSB) Certification

    All veterans can pursue VOSB certification (not just service-disabled):

    • Benefits: Access to 5% of federal contracting set-asides
    • Lender recognition: Some SBA lenders offer marginally better terms to certified VOSBs
    • Networking: Connection to veteran business owner communities and resources

    Step-by-Step Guide to Securing Your SBA Veteran Loan

    Knowing your options is half the battle. Here’s how to move from consideration to capital in your hands.

    Step 1: Assess Your Needs & Choose the Right Program

    Before approaching a lender, clarify your funding requirement:

    • Under $50,000? Consider the Microloan program
    • $50,000–$500,000? Veterans Advantage 7(a) loan
    • Over $500,000 or need real estate? 504 loan or larger 7(a)
    • Seeking grants? Explore state-specific programs and SBDC consulting (free)

    Step 2: Prepare Your Business Plan & Financial Documentation

    Lenders evaluate risk. You’ll need:

    • Personal and business tax returns (2 years minimum)
    • Detailed business plan with financial projections
    • Personal financial statement
    • Proof of military service (DD Form 214)
    • Collateral documentation (if applicable)
    • Personal credit report

    Many SBA veteran lenders have streamlined documentation for military veterans, recognizing your background demonstrates discipline and follow-through.

    Step 3: Connect with SBA-Preferred Veteran Lenders

    Not all banks offer SBA loans equally. Partner with lenders specializing in veteran funding:

    • Community Banks: Often more flexible with military-connected owners
    • SBA Premier Lenders: Streamlined approval processes
    • Veteran-Focused Lenders: Banks dedicated to military entrepreneur lending

    Glen Gould and Funding-Advisor.com can help match you with veteran-experienced lenders in your region, accelerating the approval process.

    Step 4: Apply Through SBA Portal or Directly to Lender

    You can apply directly to an SBA-approved lender (fastest) or through the SBA’s official portal. Direct lender applications typically close within 30–60 days for Veterans Advantage loans.

    Step 5: Close & Deploy Capital

    Upon approval, closing typically occurs within 2–4 weeks. Funds are then available for your intended business purpose.

    Eligibility Requirements for Veteran SBA Loans

    Basic requirements include:

    • Military Service: Honorable or General discharge (other discharges evaluated case-by-case)
    • Business Ownership: You must own 20%+ of the business (100% ownership typical for new ventures)
    • U.S. Citizenship: Citizen or permanent resident
    • Personal Guarantee: You’ll personally guarantee the loan
    • Credit: Minimum 640 credit score (varies by lender; some veteran programs more flexible)
    • Business Type: Legal, operating business (no speculation investments)

    Veterans with lower credit scores or minimal business experience should explore Microloan or SBDC consulting programs first—these programs rebuild creditworthiness while providing guidance.

    Comparing Veteran Funding Options: Interest Rates & Terms

    As of mid-2026, here’s how SBA veteran funding compares to conventional lending:

    Program Max Loan Interest Rate Range Term Best For
    Veterans Advantage (7a) $5M Prime + 2.25–2.75% 10 years (WC), 25 years (RE) General business needs
    504 Loan $5M 1–2% below prime 20 years (RE), 10 years (Equip) Real estate, equipment
    Microloan $50K 8–13% 6 years avg Startups, working capital
    Conventional Bank Loan Varies Prime + 3–5% 5–10 years Strong credit/collateral

    The SBA veteran advantage: 1–3% lower rates plus government guarantee reducing your lender’s risk—ultimately benefiting you with faster approval and more favorable terms.

    Common Mistakes Veteran Business Owners Make

    Avoid these pitfalls:

    • Incomplete documentation: Missing tax returns or business plan delays everything. Prepare thoroughly upfront.
    • Applying to non-SBA lenders first: Non-SBA lenders charge higher rates. Always explore SBA programs first.
    • Insufficient collateral planning: Some veterans underestimate collateral requirements. Clarify this early.
    • Ignoring state veteran programs: Many states (Texas, California, Florida, etc.) offer additional grants and low-interest programs uniquely for veterans.
    • Not leveraging free resources: SBDC, SCORE, and Boots to Business are free and strengthen applications significantly.

    Resources for Veteran Business Owners

    Maximize your path to funding:

    • SBA Veteran Business Outreach Center: Dedicated counseling, workshops, and resource navigation
    • SBDC Veteran Programs: Free business planning and loan preparation at your state’s Small Business Development Center
    • VA Office of Small & Disadvantaged Business Utilization: Government contracting support
    • Funding-Advisor.com: Lender matching, application tracking, and expert guidance for veteran entrepreneurs
    • State Veterans Affairs Offices: State-specific grants and contracting opportunities

    Frequently Asked Questions

    Q: Can I get an SBA loan as a veteran with no business experience?

    A: Yes. The SBA Microloan program and SBDC consulting specifically support first-time veteran entrepreneurs. Many lenders view military discipline and leadership favorably. Free training through Boots to Business and SCORE strengthens your application considerably. Start with SBDC consultation—it’s free and improves your preparation substantially.

    Q: What’s the difference between a VOSB and SDVOSB certification?

    A: VOSB (Veteran-Owned Small Business) applies to all veterans and unlocks 5% of federal contracts. SDVOSB (Service-Disabled VOSB) applies only to veterans with VA-rated service disabilities and reserves 3% of federal contracts exclusively for your business. Both enhance SBA lending options. If you qualify for SDVOSB, pursue it—it offers more exclusive contracting and sometimes better loan terms.

    Q: How long does an SBA Veterans Advantage loan take to approve?

    A: Direct SBA lender applications typically take 30–60 days from complete application to funding. Portal applications may take longer (60–90 days). Having all documentation ready—tax returns, business plan, DD-214, financial statements—cuts approval time significantly. Funding-Advisor.com can help coordinate documentation to accelerate this timeline.

    Q: Are there grants for veteran-owned businesses, or only loans?

    A: True grants to businesses are rare. However, the SBA offers free consulting (worth thousands), state programs provide grants in some states ($5K–$50K+), and corporate veteran programs offer funding and resources. Federal contracting as a certified VOSB/SDVOSB generates substantial revenue—often better than traditional loans for scaling quickly. Many veterans combine a modest SBA loan with government contracting revenue.

    Q: What credit score do I need for a veteran SBA loan?

    A: Veterans Advantage loans typically require 640+ credit score, though some lenders accept 600+. Microloans are more flexible (580+). If your credit is lower, use your free SBDC consultation to rebuild your profile before applying. Military discipline and strong business plans can offset modest credit scores when working with veteran-experienced lenders.

    Get Expert Business Funding Guidance

    Book Free Strategy Call or call 850-990-0053

    Related Reading

  • Fine-Tuning vs. RAG: Which AI Method Is Right for You?

    https://blog.n8n.io/fine-tuning-vs-rag/

    Two Powerful Approaches to Smarter AI Systems

    If you’re a business owner or investor exploring how AI can work harder for you, you’ve probably heard terms like “fine-tuning” and “RAG” thrown around. But what do they actually mean, and which one should you be using in your business? Understanding the difference can save you time, money, and a lot of frustration when building AI-powered tools for real estate, lending, or client management.

    What Is Fine-Tuning?

    Fine-tuning is the process of taking an existing large language model (LLM) — think ChatGPT or a similar AI — and training it further on your own specific data. The result is a model that has essentially “learned” your industry, your tone, and your specific use cases at a foundational level. For example, a fine-tuned model for a real estate business might naturally speak the language of cap rates, NOI, and deal structures without needing extra prompting.

    The trade-off? Fine-tuning requires a meaningful investment of time, quality training data, and technical resources. It’s also a snapshot in time — once trained, the model doesn’t automatically update when your business or market conditions change.

    What Is RAG?

    RAG stands for Retrieval-Augmented Generation. Instead of baking knowledge into the model itself, RAG allows an AI to pull relevant information from an external database or document library in real time before generating a response. Think of it like giving your AI a filing cabinet it can search through before answering a question.

    For a business owner in the Florida Panhandle, this might look like an AI assistant that can pull up current property listings, recent loan terms, or your internal SOPs before responding to a client inquiry. RAG keeps answers current and grounded in real, specific data — without requiring you to retrain a model every time something changes.

    When Should You Use Fine-Tuning?

    Fine-tuning makes the most sense when you need the AI to consistently reflect a specific style, format, or domain expertise. If you want your AI to always respond like a seasoned real estate advisor — using the right terminology, structuring answers a certain way, and maintaining a consistent tone — fine-tuning builds that capability into the model’s core behavior. It’s a strong choice when your core knowledge is relatively stable and well-documented.

    When Should You Use RAG?

    RAG shines when you need your AI to work with dynamic, frequently updated, or highly specific information. In real estate and business funding, deals change fast. Interest rates shift, properties go under contract, and underwriting guidelines get updated. RAG lets your AI stay current without starting from scratch. It’s also a more cost-effective entry point for most small business owners who want powerful AI without the overhead of a full model training process.

    Why the Best Systems Use Both

    Here’s where it gets interesting: most production-level AI systems in serious business environments use fine-tuning and RAG together. Fine-tuning handles the “how to think and respond” layer — giving the model the right persona, expertise, and communication style. RAG handles the “what to say” layer — pulling in accurate, real-time data to back up those responses.

    For a real estate investor or business owner, this combination could mean an AI that communicates like a knowledgeable advisor (fine-tuned) while pulling from your current deal pipeline, lending guidelines, or market data (RAG). The result is an AI tool that feels both intelligent and accurate — not just one or the other.

    What This Means for Your Business

    Whether you’re managing rental properties, helping clients secure business funding, or running a growing operation in Northwest Florida, AI tools built on these approaches can dramatically improve how you handle client communication, underwriting questions, and lead follow-up. The key is knowing which tool fits your problem — and understanding that you don’t always have to choose just one.

    Ready to go deeper on fine-tuning versus RAG and how each approach plays out in real production environments? Watch the full video from the n8n team for a detailed breakdown that will help you make smarter decisions about the AI tools you build or invest in for your business.

    Related Reading

  • Claude Code vs n8n: Which Tool Is Right for You?

    https://blog.n8n.io/should-i-use-claude-code-or-n8n/

    Two Powerful Tools, One Important Choice

    If you’re running a real estate investing operation or a small business in the Florida Panhandle, chances are you’re looking for ways to automate repetitive tasks and get more done with less overhead. Two tools getting a lot of attention right now are Claude Code and n8n — and knowing which one to reach for can save you serious time and money.

    Ophir Prusak, who uses both tools daily, breaks down five straightforward questions that help you figure out which one fits your specific situation. Let’s walk through what that means for real estate investors and business owners like you.

    What’s the Core Difference?

    Think of it this way: n8n is a visual workflow automation platform. You connect apps, triggers, and actions by dragging and dropping nodes on a canvas. It’s built for automating processes — things like routing leads from your website into a CRM, sending follow-up texts when a property inquiry comes in, or syncing data between platforms you already use.

    Claude Code, on the other hand, is an AI coding assistant. It writes, edits, and reasons through actual software code. It’s better suited for building something custom from scratch — a unique application, a script that does something no off-the-shelf tool can do, or a solution that requires real programming logic.

    The Five Questions Worth Asking Yourself

    1. Are you connecting existing apps or building something new? If you’re trying to get Zillow leads into your Google Sheet and then trigger an email — that’s a connection job. n8n wins. If you need a custom-built tool that doesn’t exist yet, Claude Code is your starting point.

    2. How technical are you? n8n is designed to be approachable for non-coders. You don’t need to write a line of code to build powerful automations. Claude Code requires more comfort with programming concepts, even if it handles the heavy lifting for you.

    3. Do you need to maintain this long-term? Visual workflows in n8n are easier for a team member to pick up, read, and adjust. Code produced with Claude Code can be powerful but may require someone with technical skills to update it down the road.

    4. Is speed or flexibility more important? n8n can get you up and running with an automation in an afternoon. Claude Code can build something more tailored, but it takes more iteration and testing. For most real estate and business automation needs, speed wins — and n8n delivers.

    5. What does your budget look like? n8n has a self-hosted free option and affordable cloud plans. Claude Code usage through Anthropic can add up depending on how much you’re building. For lean operations, knowing your cost structure matters.

    What This Looks Like in Real Estate

    Let’s make this practical. Say you want to automatically follow up with motivated seller leads the moment they fill out a form on your website. That’s a perfect n8n use case — connect your form tool, filter the data, send a personalized SMS or email, and log it in your CRM. Done in a few hours, no coding required.

    Now say you want to build a custom deal analyzer that pulls comps, runs your numbers, and spits out a detailed PDF report with your branding. That’s more of a Claude Code project — it requires actual programming logic and a more custom build.

    Most investors and small business owners in the Panhandle will find that n8n handles 80% of what they need to automate. Claude Code is the specialist you call in when you’ve outgrown what visual tools can do.

    The Bottom Line

    You don’t have to choose one forever. Many operators use both — n8n for day-to-day workflow automation, Claude Code when they need something truly custom built. The key is matching the right tool to the right job so you’re not overcomplicating simple problems or limiting yourself with the wrong platform.

    Ready to go deeper? Watch the full video from Ophir Prusak for a detailed walkthrough of each question and real examples of when to use each tool.

    Related Reading

  • How to Dispute Business Credit Report Errors

    How to Dispute Business Credit Report Errors

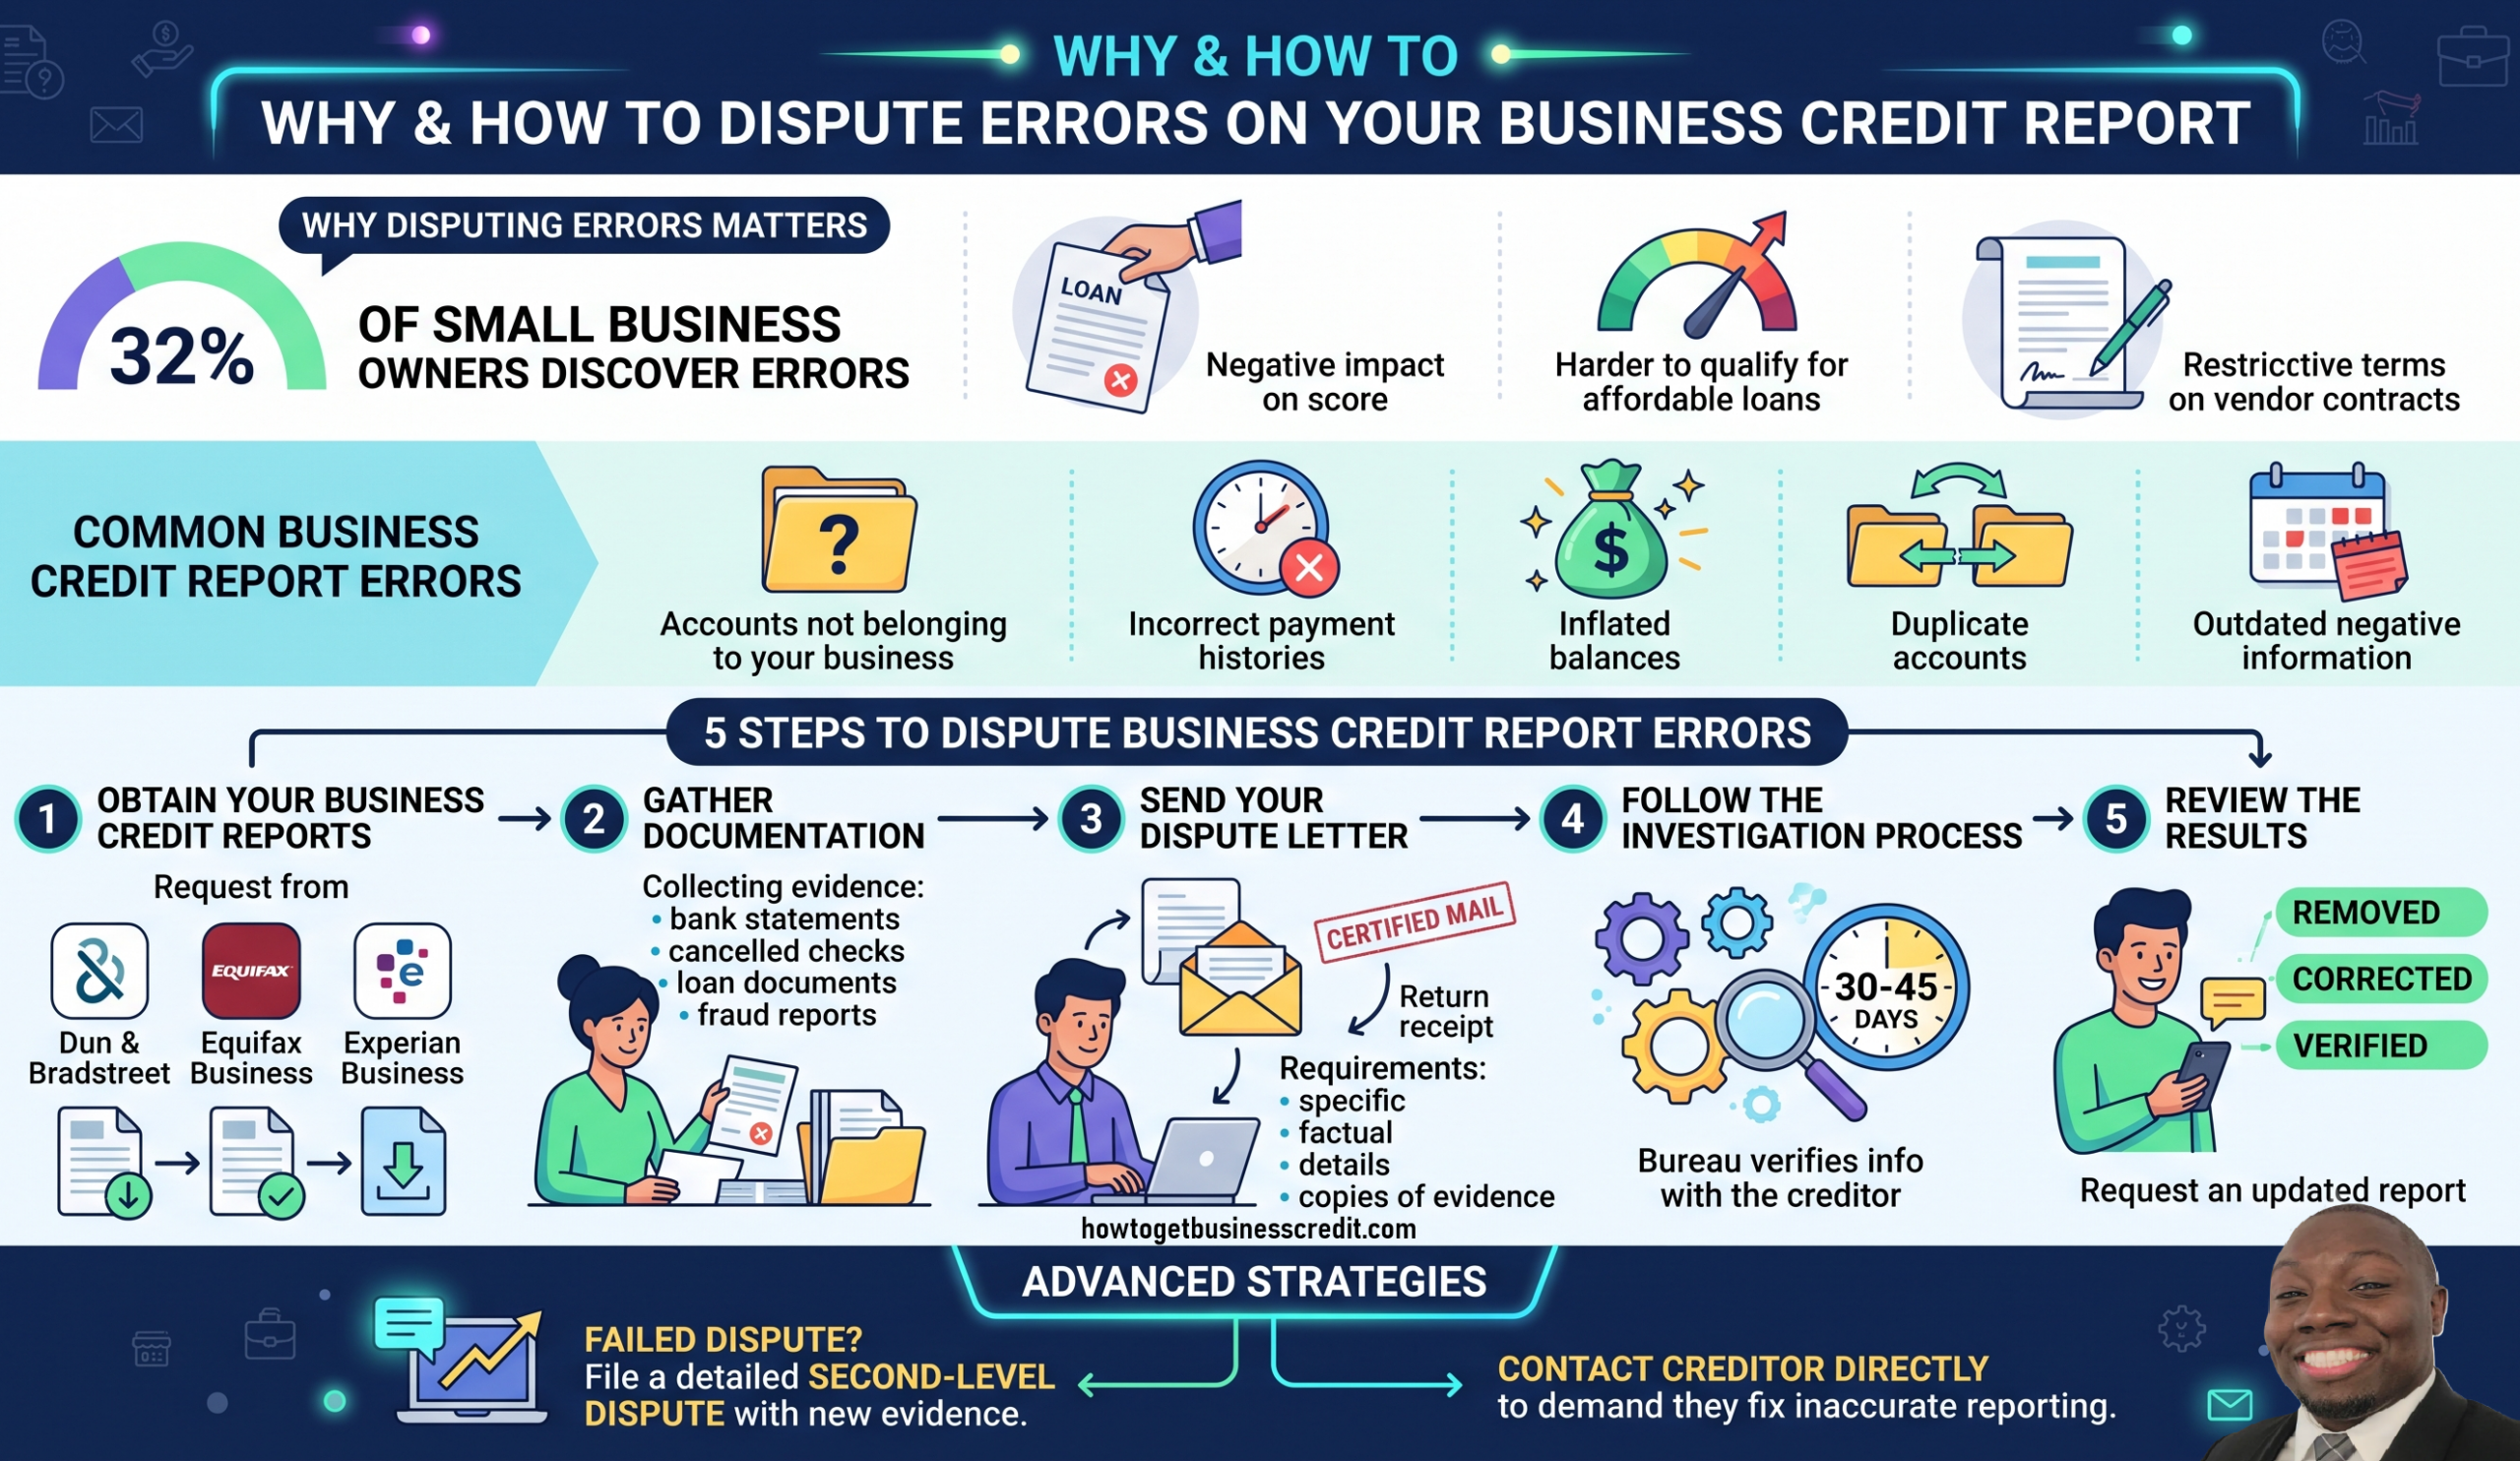
    Quick Answer: You can dispute business credit report errors by contacting the credit reporting agency in writing within 30 days, providing documentation of the inaccuracy, and requesting removal or correction. The dispute process typically takes 30-45 days, and success rates improve significantly when you include supporting evidence like bank statements or payment records.

    How to Dispute Business Credit Report Errors

    Your business credit report is one of the most critical financial documents you’ll encounter as a small business owner. Lenders, suppliers, and creditors use it to evaluate your creditworthiness when you apply for SBA loans, vendor credit lines, or equipment financing. Unfortunately, errors on your business credit report are more common than you might think—and they can cost you thousands of dollars in higher interest rates or denied funding requests.

    According to the National Small Business Association, approximately 32% of small business owners discover errors on their business credit reports. These mistakes can range from accounts you don’t recognize to incorrect payment histories or outdated negative information. The good news? You have legal rights to dispute these errors and get them corrected.

    This comprehensive guide will walk you through the entire process of disputing business credit report errors, protecting your access to affordable capital, and ensuring your financial reputation accurately reflects your business practices.

    Understanding Business Credit Report Errors

    Common Types of Errors

    Business credit errors fall into several categories, each requiring different dispute strategies. Understanding which type of error you’re facing helps you build a stronger dispute case and increases your chances of successful resolution.

    Account Errors: The most common mistake is accounts listed that don’t belong to your business. This might include accounts opened by someone using your EIN fraudulently, merged accounts from previous business structures, or accounts from another business with a similar name. These errors are particularly damaging because they suggest you have obligations you’ve never actually incurred.

    Payment History Errors: Incorrect payment status notations are surprisingly frequent. You might see accounts marked as 30, 60, or 90 days late when you actually paid on time, or accounts showing as delinquent when you’ve maintained a current status. These errors directly impact your credit score and your ability to qualify for SBA loans with favorable terms.

    Balance Errors: Sometimes credit bureaus report incorrect outstanding balances on active accounts. This inflates your debt-to-income ratio and makes you appear riskier to lenders than you actually are. If you’re seeking a $250,000 SBA 7(a) loan, an inflated balance of even $50,000 could affect your approval odds.

    Duplicate Accounts: Your business might appear to have the same account listed multiple times, which artificially increases your reported debt and creates confusion about your actual credit obligations.

    Outdated Information: Negative information like charge-offs, collections, or late payments should eventually fall off your report. Federal law requires derogatory items to be removed after 7 years from the original delinquency date. If you’re seeing older negative marks, those are errors you can successfully dispute.

    Why These Errors Matter

    Business credit errors directly impact your ability to access affordable capital. An error that lowers your business credit score by 50 points could increase your SBA loan interest rate by 1-2%, meaning you’d pay tens of thousands in additional interest over a 10-year repayment period on a $500,000 loan.

    Beyond loan rates, these errors affect your ability to:

    • Establish vendor credit lines that don’t require upfront payment
    • Negotiate better payment terms with suppliers
    • Qualify for equipment leasing or financing
    • Secure commercial insurance at competitive rates
    • Attract potential business partners or investors

    Step-by-Step Guide to Disputing Business Credit Report Errors

    Step 1: Obtain Your Business Credit Report

    Before you can dispute errors, you need to see what’s being reported about your business. Unlike personal credit, there’s no single “free” business credit report you’re entitled to annually. However, the major business credit bureaus—Dun & Bradstreet, Equifax Business, and Experian Business—all provide access to your business credit reports, typically for a fee of $20-$75 per report.

    Glen Gould recommends requesting reports from all three bureaus, as they often have different information. An error on one bureau’s report might not appear on another’s, so checking all three ensures you catch everything.

    When you receive your reports, review them carefully for:

    • Incorrect business name, address, or phone number
    • Wrong EIN or tax ID number
    • Accounts you don’t recognize
    • Inaccurate payment histories
    • Incorrect balance amounts
    • Information that should have been removed (older than 7 years)

    Step 2: Gather Documentation

    Your dispute will be much more effective when you include supporting evidence. Strong documentation dramatically increases the likelihood of successful resolution. Collect the following materials:

    For Payment Disputes: Bank statements showing the payment was made, cancelled checks, payment receipts from the creditor, or ACH transfer confirmations. Keep these organized chronologically to show your payment pattern.

    For Account Disputes: Original credit applications (or their absence if you never applied), correspondence with the creditor, and any fraud reports you’ve filed with law enforcement or the Federal Trade Commission.

    For Balance Disputes: Recent statements from the actual creditor showing your current balance, loan documents showing the original loan amount, and payment records demonstrating how much you’ve paid down.

    For Duplicate Accounts: Account numbers from your statements, any correspondence from the creditor about account consolidation, and documentation showing these are the same obligation.

    Step 3: Send Your Dispute Letter

    Federal law (the Fair Credit Reporting Act) requires you to send your dispute in writing. While phone calls or online disputes might be available, a written letter creates a paper trail and ensures your dispute is documented.

    Your dispute letter should:

    • Be Specific: Don’t just say “this is wrong.” Clearly state what information is inaccurate and what the correct information should be.
    • Include Your Business Information: Your business name, EIN, phone number, and the address on file
    • Reference the Disputed Account: Include the account number or creditor name from the credit report
    • Request Verification: Ask the bureau to verify the information with the reporting creditor and remove it if it cannot be verified
    • Be Professional: Keep emotions out of the letter and stick to facts
    • Include Copies (Not Originals): Attach copies of your supporting documentation
    • Request Confirmation: Ask the bureau to send you written confirmation once the dispute is resolved

    Send your letter via certified mail with return receipt requested to:

    • Dun & Bradstreet: Disputes Department, 103 JWL Drive, Wilmington, DE 19801
    • Equifax Business: Equifax Business Disputes, P.O. Box 740256, Atlanta, GA 30374
    • Experian Business: Experian Business Disputes, P.O. Box 9701, Allen, TX 75013

    Step 4: Follow the Investigation Process

    Once the credit bureau receives your dispute, they have 30-45 days to investigate. During this period, they contact the creditor reporting the information and ask them to verify its accuracy. If the creditor cannot verify the information within the timeframe, the bureau must remove it.

    Many disputes are resolved successfully during this period simply because creditors don’t respond to verification requests quickly or at all. This is where having detailed documentation becomes crucial—creditors are more likely to respond when a bureau inquiry comes with your supporting evidence attached.

    Step 5: Review the Results

    The credit bureau will send you written results of their investigation. They might:

    • Remove the Information: The best outcome—the error is deleted from your report entirely
    • Correct the Information: The item stays but with accurate details (different balance, correct payment status, etc.)
    • Verify the Information: The bureau confirms the information is accurate. If you disagree, you can request a second-level dispute

    If the dispute is resolved in your favor, ask the bureau to send an updated copy of your credit report and provide copies to any creditors who received the inaccurate information in the past 6 months.

    Advanced Dispute Strategies for Persistent Errors

    Second-Level Disputes

    If the bureau’s initial investigation doesn’t resolve the issue or you disagree with their findings, you have the right to file a second-level dispute. This is particularly useful when:

    • The creditor verifies information you believe is incorrect
    • You have additional documentation you didn’t include in the first dispute
    • The bureau failed to investigate thoroughly

    Your second-level dispute should be more detailed, highlighting specifically why you believe the bureau’s investigation was inadequate and including any new evidence.

    Direct Creditor Disputes

    While disputing with the credit bureau is important, also dispute directly with the creditor reporting the error. Send them a certified letter explaining the inaccuracy and requesting they contact the credit bureau to correct or remove the information. Some creditors respond faster to direct contact than they do to bureau verification requests.

    Working with Funding-Advisor.com for Complex Cases

    For disputes involving fraud, identity theft, or particularly damaging errors, consider getting professional assistance. Funding-Advisor.com can help you navigate complex disputes and ensure your business credit is restored to where it should be, making you more competitive for SBA loans and other capital.

    Protecting Your Business Credit Going Forward

    Monitor Regularly

    Don’t wait years to discover errors. Check your business credit reports at least annually—more frequently if you’ve had disputes in the past. Many business credit bureaus offer affordable monitoring services that alert you to changes.

    Maintain Documentation

    Keep copies of all business credit applications, statements, payment confirmations, and correspondence with creditors for at least 7 years. This documentation makes future disputes much easier to resolve.

    Optimize Your Business Credit Profile

    Beyond disputing errors, actively improve your business credit by:

    • Paying all invoices on time
    • Maintaining low credit utilization (ideally below 30%)
    • Keeping business credit accounts open even when inactive
    • Regularly reviewing your business credit reports

    How Corrected Business Credit Impacts Your Funding

    Correcting errors on your business credit report can have dramatic effects on your access to capital. Consider this example: a business with a credit score of 60 would struggle to qualify for an SBA loan. If that low score was due to an error that you successfully dispute, your score might jump to 75-80, making you eligible for SBA 7(a) loans up to $5 million with rates typically ranging from 7-10% depending on your term length and down payment.

    For a $250,000 SBA loan over 10 years, the difference between a 9% and 11% interest rate (potentially caused by the credit error) is approximately $24,000 in additional interest paid. Disputing the error not only fixes your reputation—it saves you significant money.

    Frequently Asked Questions

    Q: How long does a business credit dispute take?

    A: The initial investigation period is 30-45 days from when the credit bureau receives your dispute. However, actual resolution can take 60-90 days depending on how quickly creditors respond to verification requests and whether you need to file second-level disputes.

    Q: Can I dispute business credit errors online?

    A: While some credit bureaus offer online dispute tools, sending a written certified letter is more effective and creates better documentation. Consider using both methods to maximize your chances of resolution.

    Q: What if the creditor won’t remove the error?

    A: If you believe a creditor is deliberately reporting false information, you can file a complaint with the Consumer Financial Protection Bureau (CFPB) or your state’s attorney general office. You also have the right to add a statement to your credit report explaining the dispute.

    Q: Does disputing hurt my business credit score?

    A: No, disputing an error does not hurt your credit score. The dispute inquiry itself is not reported to other creditors and does not trigger a hard inquiry that affects your score.

    Q: How can I get a loan while disputing errors?

    A: You can apply for SBA loans during the dispute process, though approval might be delayed until the dispute is resolved. Lenders often wait for resolution of significant disputes before finalizing funding. Disclose the dispute in your loan application to maintain transparency with lenders.

    Get Expert Business Funding Guidance

    Book Free Strategy Call or call 850-990-0053

    Related Reading

  • Compliance Automation Software: What to Evaluate

    https://blog.n8n.io/compliance-automation-software/

    Why Compliance Automation Matters for Real Estate and Business Owners

    If you’re running a real estate investment business or managing a growing company in Florida, compliance isn’t optional — it’s the foundation that keeps your deals closing, your licenses intact, and your liability exposure manageable. The problem is that keeping up with ever-changing regulations manually is a time drain that pulls you away from the work that actually generates revenue. That’s where compliance automation software comes in, and knowing how to evaluate your options can save you thousands of dollars and countless headaches.

    What Compliance Automation Software Actually Does

    At its core, compliance automation software handles the repetitive, rule-based tasks that your team would otherwise do by hand — things like document verification, audit trail generation, regulatory reporting, and policy enforcement. For real estate investors, this might mean automating title search workflows, tracking disclosure requirements across multiple transactions, or flagging deals that don’t meet lending compliance standards. For business owners seeking funding, it can mean keeping your financial documentation audit-ready without dedicating staff hours to manual data gathering.

    The right platform doesn’t just automate tasks — it builds a documented, repeatable process that holds up under scrutiny. That matters when you’re in front of a lender, a regulator, or a potential business partner.

    Key Features to Look For

    Not all compliance tools are built the same way, and the wrong choice can lock you into a rigid system that doesn’t scale with your business. Here are the core features worth evaluating before you commit:

    Workflow flexibility. Your compliance needs will evolve. A platform that lets you customize and adapt workflows — without requiring a developer every time — is far more valuable than a rigid out-of-the-box solution. Look for visual workflow builders that let non-technical users make adjustments as regulations change.

    Integration capability. Compliance doesn’t live in a silo. You need software that connects with the tools you’re already using — your CRM, your accounting platform, your document management system. If your compliance tool can’t talk to your other systems, you’ll end up with data gaps and manual workarounds that defeat the purpose.

    Data control and infrastructure ownership. This is a big one that often gets overlooked. Many SaaS compliance platforms store your sensitive data on their servers, which introduces third-party risk and can create complications in regulated industries. Platforms like n8n offer self-hosted options, meaning you run the automation on your own infrastructure and maintain full control over your data. For real estate investors handling sensitive financial and personal information, that distinction matters.

    Audit trail and reporting. Any serious compliance tool should automatically generate logs of every action taken, every decision made, and every document processed. When an auditor or lender asks you to demonstrate your compliance history, you want to pull a clean, timestamped report — not scramble through email threads.

    The Trade-Offs You Need to Understand

    Every compliance automation platform involves trade-offs, and being honest about your situation upfront will save you from expensive mistakes later. Fully managed SaaS solutions are easier to set up but often come with higher long-term costs, limited customization, and the data sovereignty concerns mentioned above. Self-hosted or open-source platforms like n8n require more initial setup but give you flexibility, control, and often a lower total cost of ownership as your business scales.

    For small to mid-sized real estate businesses and growing companies in the Florida Panhandle, the sweet spot is usually a platform that offers pre-built templates and integrations to get you started quickly, combined with the ability to build custom workflows as your specific compliance requirements become clearer.

    Building Workflows That Work for Your Business

    The best compliance automation strategy isn’t about finding perfect software — it’s about building workflows that match how your business actually operates. Start by mapping out your highest-risk, most time-consuming compliance tasks. Prioritize automating those first. Then expand as your confidence in the system grows. The goal is a compliance process that runs in the background while you focus on closing deals and growing your portfolio.

    Ready to go deeper on how to evaluate and implement compliance automation for your business? Watch the full video from the n8n team for a detailed breakdown of features, platform comparisons, and practical workflow-building strategies you can apply right away.

    Related Reading

  • How to Get an SBA Loan With No Collateral Required

    Quick Answer: You can obtain SBA loans without collateral through unsecured microloan programs, Community Advantage loans, and express lending options where the SBA guarantees up to 90% of your loan. These programs prioritize business cash flow and creditworthiness over physical assets, making them ideal for startups and businesses without significant tangible assets.

    How to Get an SBA Loan With No Collateral Required

    One of the biggest misconceptions about SBA loans is that you need substantial collateral to qualify. The reality is far more encouraging: thousands of small business owners secure SBA funding every year without pledging real estate, equipment, or inventory. Understanding your collateral-free options can open doors to capital you didn’t know existed.

    The SBA (Small Business Administration) has designed multiple lending programs specifically to help entrepreneurs access funding without traditional collateral requirements. Whether you’re launching a startup, scaling operations, or facing cash flow challenges, these programs provide pathways to capital when traditional banks won’t budge.

    Understanding SBA Loan Collateral Requirements

    Why Collateral Matters to Lenders

    Traditional bank loans rely heavily on collateral as security. Lenders want to know they can recover their investment if you default. However, SBA loans work differently. The federal government guarantees a portion of the loan (typically 75-90%), which significantly reduces the lender’s risk. This guarantee structure means collateral becomes far less critical to approval.

    The SBA Guarantee Advantage

    When the SBA guarantees 75-90% of a loan, lenders are protected against most losses. This safety net means they’re willing to approve loans based on other factors: your personal credit score, business cash flow, industry experience, and character. The SBA’s guarantee essentially replaces collateral as the primary risk mitigator.

    Personal Guarantees vs. Collateral

    Here’s an important distinction: most SBA loans require a personal guarantee from the business owner, but this is different from collateral. A personal guarantee means you’re personally liable if the business can’t repay, but the lender won’t seize specific assets upfront. They can pursue legal action if default occurs, but approval doesn’t depend on owning valuable property or equipment.

    SBA Loan No Collateral Options You Can Access Today

    SBA Microloan Program (7(m) Loans)

    The SBA Microloan program is perhaps your best no-collateral option. These loans max out at $50,000 and are distributed through nonprofit intermediaries approved by the SBA. Here’s what makes them attractive for collateral-free borrowing:

    • Minimal Asset Requirements: Lenders focus on business potential, not collateral
    • Lower Loan Amounts: Because amounts are capped at $50,000, risk is naturally limited
    • Flexible Underwriting: Intermediaries understand startup challenges and accept alternative credit histories
    • Typical Interest Rates: 8-15% depending on the intermediary and your credit profile
    • Repayment Terms: Up to 6 years for working capital, up to 10 years for equipment

    To qualify, you’ll need a business plan, personal credit score of 580+, and a viable business concept. Many microloan intermediaries also provide free business training, helping you strengthen your application and business foundation.

    Community Advantage Loan Program

    This SBA program specifically targets entrepreneurs who don’t qualify for traditional loans, including those without collateral. Community Advantage loans top out at $250,000 and emphasize creditworthiness over assets.

    • Interest Rate Range: 7.25% to 11.25%, typically lower than microloans
    • Loan Amounts: $250,000 maximum
    • Underwriting Standards: More flexible than conventional SBA loans
    • Credit Score Minimums: As low as 640 possible with strong compensating factors
    • Technical Assistance: Free business counseling often included

    Community Advantage loans are delivered through certified community development financial institutions (CDFIs). These lenders understand small business challenges and are specifically trained to work with entrepreneurs who have limited collateral.

    SBA Express Loans

    While Express loans aren’t exclusively designed for no-collateral borrowing, many lenders approve them without requiring substantial assets. These loans offer:

    • Faster Turnaround: As quick as 36 hours for approval
    • Loan Amounts: Up to $350,000
    • SBA Guarantee: 50% guarantee (lower than other programs but still significant)
    • Interest Rates: Typically 2.5% to 4% above the prime rate
    • Flexible Collateral: Many lenders will work with minimal collateral or accept personal guarantees alone

    The trade-off with Express loans is a lower SBA guarantee percentage, but the speed and accessibility make them attractive for businesses needing capital quickly.

    Alternative No-Collateral Funding Strategies

    Equipment Financing as a Workaround

    If you need capital for equipment purchases, equipment financing doesn’t require traditional collateral. Instead, the equipment itself serves as collateral, meaning you’re not putting personal or business assets at risk beyond the equipment being financed. SBA loans specifically designed for equipment purchases (Part 504 loans through Community Development Companies) can be structured this way.

    Line of Credit Without Collateral

    Some SBA-approved lenders offer unsecured business lines of credit up to $50,000-$100,000. While these typically require stronger credit scores (680+), they’re genuine no-collateral options. These work similarly to personal credit cards but at lower interest rates and with higher limits.

    Invoice Factoring and Asset-Based Lending

    Invoice factoring allows you to access capital by selling invoices at a discount. This isn’t technically an SBA loan, but it’s an alternative funding method that doesn’t require traditional collateral. You’re essentially using your accounts receivable as the asset base.

    Steps to Qualify for SBA Loans Without Collateral

    Step 1: Prepare Your Financial Documentation

    Lenders will scrutinize your finances to compensate for the lack of collateral. Prepare:

    • 2 years of personal tax returns
    • 2-3 months of business bank statements
    • Profit and loss statements (for existing businesses)
    • Business balance sheet
    • List of business debts and obligations
    • Detailed personal financial statement

    Step 2: Strengthen Your Credit Profile

    Without collateral, your creditworthiness becomes paramount. Review your personal credit report and address any errors. If your score is below 640, consider:

    • Paying down existing debts
    • Correcting late payments or collections
    • Keeping credit card utilization below 30%
    • Building credit history for 6+ months before applying

    For microloans, you might qualify with a 580 credit score if other factors are strong. Glen Gould specializes in helping entrepreneurs improve their business credit profiles specifically for SBA loan qualification.

    Step 3: Develop a Compelling Business Plan

    Your business plan replaces collateral as evidence of viability. Include:

    • Executive summary of your business concept
    • Market analysis and competitive positioning
    • Detailed financial projections (3 years minimum)
    • Marketing and sales strategy
    • Management team background and experience
    • Explanation of how you’ll use the loan proceeds

    Step 4: Demonstrate Industry Experience

    Lenders want to know you understand your industry. Document:

    • Years of relevant work experience
    • Certifications or specialized training
    • Industry connections and partnerships
    • Previous business ownership experience

    Step 5: Choose the Right Lender

    Not all SBA-approved lenders are created equal. Some specialize in no-collateral lending while others focus on larger deals with substantial assets. Research:

    • Community banks and credit unions (often more flexible)
    • CDFI lenders specializing in Community Advantage loans
    • Nonprofit microloan intermediaries
    • Online SBA lenders with faster turnarounds

    Common Obstacles and How to Overcome Them

    Limited Business History

    Startups and young businesses face the biggest collateral challenges. Solutions include:

    • Pursuing microloans designed for early-stage companies
    • Adding an experienced co-owner or business partner to strengthen the application
    • Seeking a business mentor through SCORE or SBA resources
    • Demonstrating pre-sales or letters of intent from customers

    Weak Personal Credit Score

    A credit score below 640 makes traditional loans difficult but isn’t a dealbreaker. Options include:

    • Applying for microloans (accepting rates as high as 15%)
    • Having a guarantor with stronger credit join the application
    • Focusing on cash flow documentation rather than credit repair timelines
    • Waiting 3-6 months to rebuild credit while preparing other application materials

    Inconsistent Income or Business Cash Flow

    Seasonal or variable income doesn’t automatically disqualify you. Address it by:

    • Providing 2+ years of historical financials showing patterns
    • Projecting conservative future growth based on data
    • Demonstrating how the SBA loan will stabilize operations
    • Showing multiple revenue streams or client diversity

    Real Numbers: SBA Loan Rates and Terms in 2026

    As of mid-2026, SBA loan terms for no-collateral options look like this:

    • SBA 7(a) Standard Loans: Interest rates at prime + 2.25% to 2.75% (currently 9.5-10%)
    • SBA Express: Interest rates at prime + 2.5-4.75% (currently 9.75-11.25%)
    • SBA Microloans: Interest rates 8-15% depending on intermediary
    • Community Advantage: Interest rates 7.25-11.25%
    • SBA Guaranty Fees: 2-3.75% of the guaranteed portion, typically included in interest rate

    Repayment terms extend up to 10 years for working capital and up to 25 years for real estate purchases (though real estate typically requires collateral). Most no-collateral loans max out at 6-10 year terms.

    Why Work With a Business Funding Advisor

    Navigating SBA loan programs without collateral can feel overwhelming. Different lenders have different appetites for risk, and applying to the wrong lender wastes time and can negatively impact your credit. A funding advisor like those at Funding-Advisor.com can:

    • Match you with lenders most likely to approve no-collateral loans
    • Help strengthen your application before submission
    • Explain trade-offs between different SBA programs
    • Prepare you for lender conversations and questions
    • Identify the optimal loan program for your specific situation

    The best time to talk to an advisor is before you apply, not after rejection.

    Frequently Asked Questions

    Q: Can I get an SBA loan with zero collateral and zero personal guarantee?

    A: No. While you don’t need physical collateral (real estate, equipment, inventory), virtually all SBA loans require a personal guarantee from the business owner. This means you’re personally liable if the business defaults, but your personal assets aren’t seized upfront. The personal guarantee is about accountability, not collateral security.

    Q: What credit score do I need for an SBA loan with no collateral?

    A: Microloan programs accept credit scores as low as 580, while Community Advantage programs typically require 640+. However, these are minimums, not guarantees. Strong business fundamentals and cash flow can compensate for lower credit scores. Your best strategy is to improve your credit score while simultaneously preparing strong financial documentation.

    Q: How long does it take to get approved for an SBA microloan?

    A: Microloan approval typically takes 2-4 weeks after submission. SBA Express loans can be approved in as little as 36 hours. Standard SBA 7(a) loans usually take 4-6 weeks. Timeline varies based on lender responsiveness and how quickly you provide requested documentation.

    Q: If I’m denied for an SBA loan, can I reapply with a different lender?

    A: Yes, absolutely. Multiple SBA-approved lenders exist, and they have different lending criteria. A rejection from one lender doesn’t mean you’ll be rejected everywhere. In fact, we recommend applying to 2-3 appropriate lenders simultaneously to increase approval chances. However, space out applications by a few weeks to minimize the impact on your credit report.

    Q: What happens if my business can’t repay the SBA loan?

    A: If you default, the SBA will pursue legal action to collect the debt. Since you signed a personal guarantee, they can go after your personal assets through wage garnishment, bank account levies, or liens on property. The SBA has strong collection authority. However, many lenders work with struggling borrowers on payment modifications or deferment before taking legal action.

    Get Expert Business Funding Guidance

    Book Free Strategy Call or call 850-990-0053

    Related Reading

  • AI Incident Response Workflows for Business Owners

    https://blog.n8n.io/building-an-ai-powered-incident-response-workflow-in-n8n/

    What Happens When Your Business Gets Hit by a Cyber Threat?

    If you own a business or manage commercial real estate in the Florida Panhandle, cybersecurity probably isn’t the first thing on your mind. But here’s the reality: a single data breach, ransomware attack, or network intrusion can freeze your operations, expose sensitive client information, and cost you thousands of dollars in downtime and recovery. The question isn’t whether threats will come — it’s whether your team can respond fast enough when they do.

    That’s exactly the problem this video tackles, and the solution is surprisingly accessible even for business owners who aren’t tech experts.

    What Is an AI-Powered Incident Response Workflow?

    An incident response workflow is basically a step-by-step playbook your team follows when a security threat is detected. Traditionally, this process is slow, manual, and dependent on your most experienced IT staff being available at the right time. With AI automation tools like n8n, you can build a system that does much of the heavy lifting automatically.

    The workflow demonstrated in this video combines three powerful elements: RAG (Retrieval-Augmented Generation), threat intelligence feeds, and historical incident data. Together, these tools allow an AI system to not only detect a threat but also pull in relevant context, compare it to past incidents, and generate a recommended response — all within minutes.

    Think of it like having a seasoned security analyst available 24/7 who never gets tired and can cross-reference thousands of past cases instantly.

    Why This Matters for Florida Business Owners and Investors

    Whether you’re running a property management company, a real estate investment operation, a small business, or overseeing commercial properties across the Panhandle region, you likely handle sensitive financial and client data every single day. Lenders, title companies, tenants, and business partners all trust you with that information.

    Slow incident response is one of the most expensive mistakes a business can make. Studies consistently show that the longer a breach goes undetected or unresolved, the higher the total cost — in regulatory fines, legal liability, client churn, and reputation damage. An automated AI workflow can cut your mean time to respond dramatically, even if you don’t have a full IT department.

    Beyond security, the broader lesson here is about automation. If AI tools can streamline something as complex as cybersecurity investigations, imagine what they can do for your leasing processes, tenant communications, financial reporting, or loan documentation workflows.

    How n8n Makes Automation Accessible

    n8n is an open-source workflow automation platform that lets you connect apps, APIs, and AI models without writing complex code. The incident response workflow in this video uses n8n to connect a monitoring trigger, a threat intelligence API, a vector database for RAG, and a language model — all in a visual drag-and-drop interface.

    For business owners, the takeaway is this: powerful AI automation is no longer reserved for large enterprises with big IT budgets. Platforms like n8n are making it possible for small and mid-sized operations to build smart, responsive systems at a fraction of the traditional cost.

    You don’t have to build this yourself, either. Working with a tech-savvy advisor or consultant who understands both your business model and these tools can get you up and running quickly.

    Key Takeaways for Your Business

    First, take cybersecurity seriously — especially if you’re handling financial transactions, real estate closings, or business funding arrangements where sensitive data flows regularly. Second, explore workflow automation tools like n8n that can help your team work smarter and respond faster to any kind of business disruption. Third, understand that AI is not just for tech companies. It’s a practical tool that’s already helping business owners in every industry operate more efficiently and protect what they’ve built.

    The Florida Panhandle business community is growing fast, and so are the threats and opportunities that come with that growth. Staying ahead means being willing to adopt smarter systems.

    Watch the full video to see exactly how this AI incident response workflow is built step by step — it’s a practical, eye-opening look at where business automation is headed and how you can start applying these ideas today.

    Related Reading